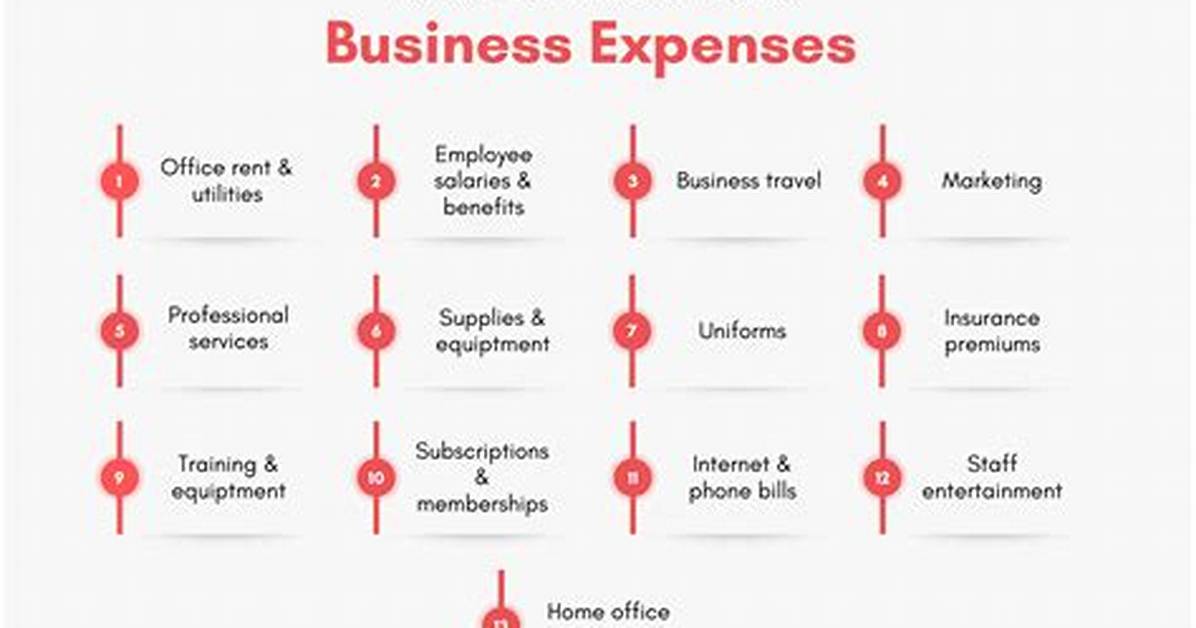
Are All Corporate Expenses Tax-Deductible?
The IRS established its position in Rev. Rul. 84-68 and confirmed that Subsidiary is entitled to a deduction under Sec. 162 if payment by Subsidiary would have resulted in such deduction.

The IRS established its position in Rev. Rul. 84-68 and confirmed that Subsidiary is entitled to a deduction under Sec. 162 if payment by Subsidiary would have resulted in such deduction.

Alexander Ross has covered the video game industry for a decade, writing deep dives on game design, esports tournaments, VR developments, and gaming culture.
Read More →