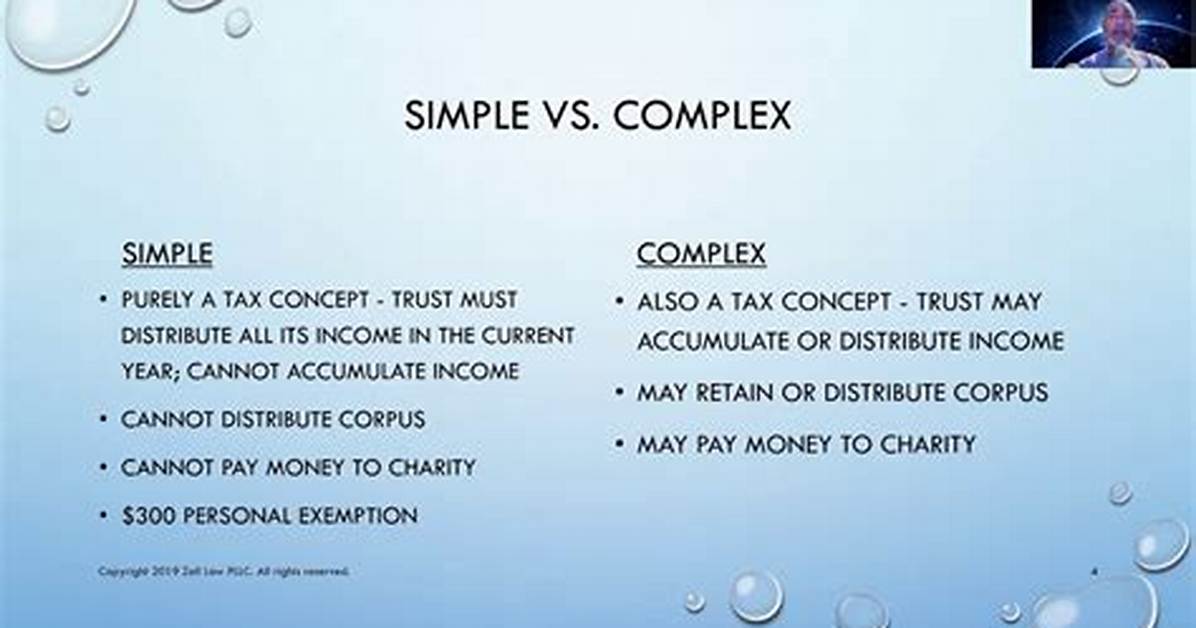
Can a Complex Trust Pass Through Capital Gains?
Trusts and estates pay capital gains taxes at a rate of 15% for gains between $2,600 and $13,150, and 20% on capital gains above $13,150.00.
How are capital gains allocated in a trust?
Method 1: Capital gains allocated to income. This method is limited unless the trust instrument or state law allocates capital gains to income, which is unlikely in most instances, or the fiduciary has broad discretion to allocate capital gains to income.
Can a trust treat capital gains as DNI?
The panel will review the requirements within trust documents to allow treating capital gains as DNI and explore state and local requirements for inclusion of capital gains in fiduciary accounting income (FAI) where the trust’s governing document does not contain such a provision.
How are capital gains included in fiduciary accounting?
Most practitioners assume (properly) that in a plain vanilla trust and under most state laws, capital gains usually are not included in fiduciary accounting income or DNI, so it is unlikely in a plain vanilla trust for capital gains to be included in income or DNI for item 1.