Can You Adjust Parent Plus Loans?
A Parent PLUS loan interest rate might be higher than the rate on other possible sources of financing. For example, parents who are homeowners may be able to take a cash-out refinance mortgage at a lower rate. Parent PLUS loans also come with an origination fee – currently 4.236% – that is deducted before the loan is disbursed.
How are PLUS loans different from student loans?
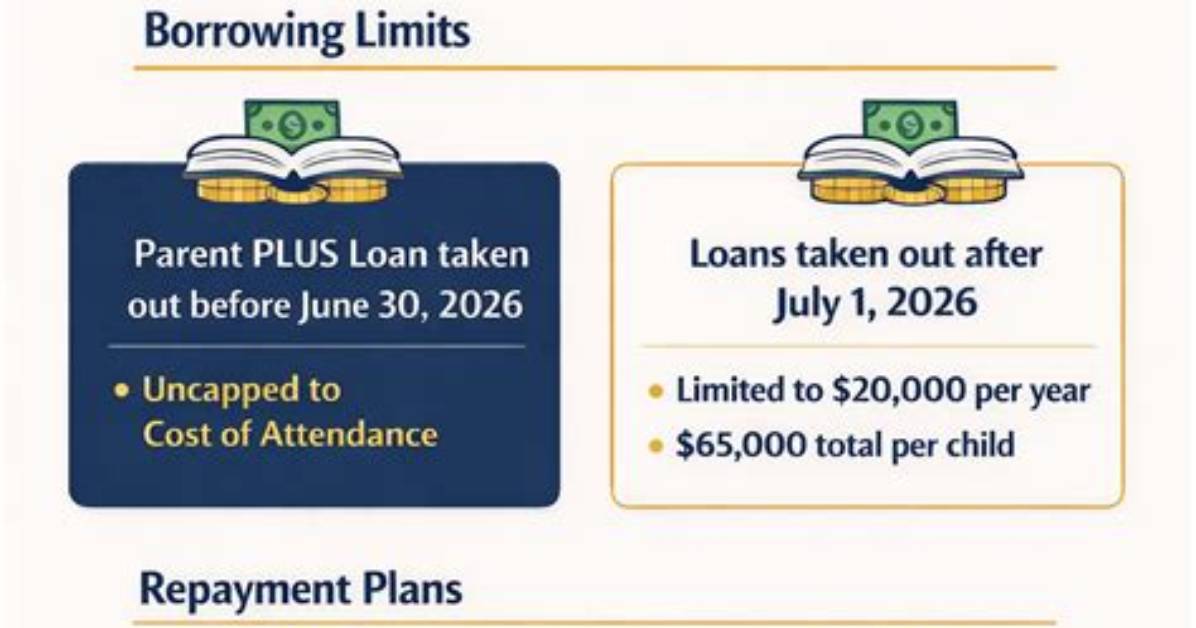
1 PLUS loans are federal loans that parents can take out to cover their child’s college costs. 2 The parent, not the student, is responsible for repaying the PLUS loan. 3 PLUS loans do not qualify for all the income-driven repayment plans that student loans do. 4 PLUS loans have large borrowing limits, making it possible to take on too much debt.
Can a parent default on a Parent PLUS loan?
Unlike student loans, with Parent Plus, it’s difficult to get a payment plan based on a family’s income. That means that if a parent loses a job or suffers a significant pay cut they may be stuck with monthly bills that they cannot afford. More than 1 in 8 parents will default on the loans, according to the most recent government estimates.
Is there Statute of limitations on Parent PLUS loans?
Private student loan lenders do not have the same garnishment powers. “There is a statute of limitations on collection for private loans, but not on federal loans,” says Gaudreau. Parent PLUS loans are forgiven if either the student or the parent borrower dies.