How Are Shareholder Distributions Taxed in a S Corporation?
S corporations are subject to special limitations on the number and type of shareholders. For example, a corporation or institutional investor may not be a shareholder in an S corporation because Subchapter S of the Code only permits individuals and certain trusts to be S corporation shareholders.
Is the C corporation income taxed at the corporate level?
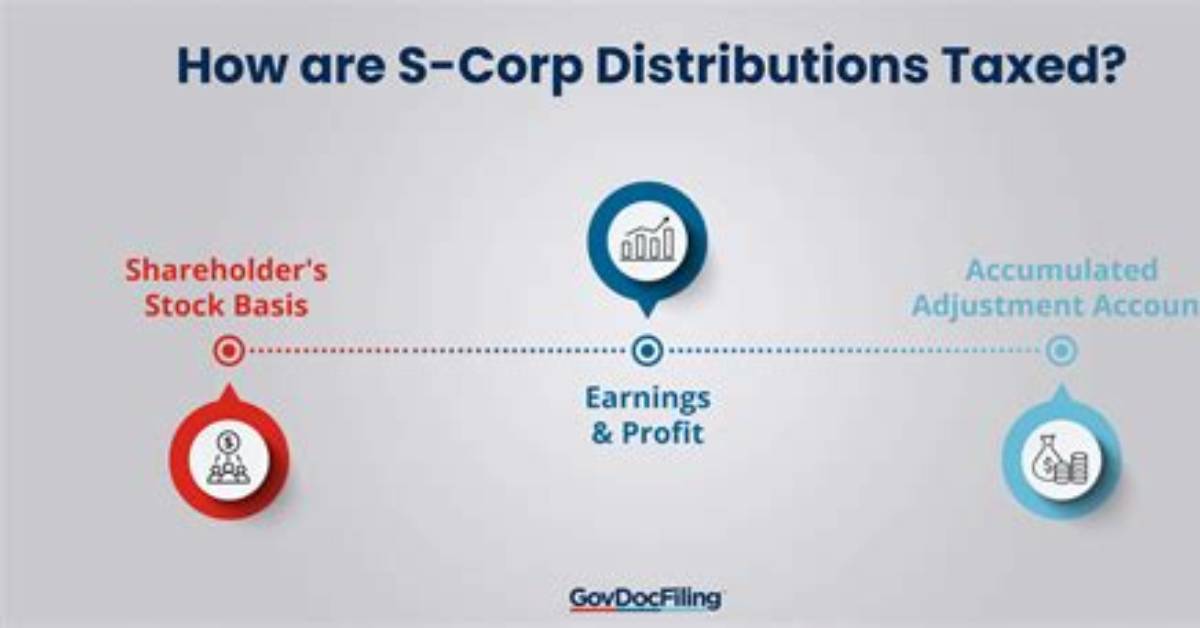
C Corporation income is first taxed at the corporate level and then, when distributed to the shareholders, taxed again as a dividend. When an S Corporation distributes its income to the shareholders, the distributions are tax-free. Or are they? As one of my partners often reminds me, the answer to every tax questions is “It depends.”
How are distributions determined if S corporation does not have ae & P?
If an S Corporation does not have AE&P, the taxability of distributions is determined solely by reference to the shareholder’s stock basis. Any distributions will be a tax-free reduction of the shareholder’s basis. Any distribution in excess of the shareholder’s stock basis is treated as capital gain from the deemed disposition of stock.
How is a C Corp dividend reported to shareholders?
A regular C corporation distributing its earnings out of retained earnings is considered a dividend. C corp shareholders receive Form 1099-DIV and they will, in turn, report the dividend on their individual federal tax return. S corporations, in general, do not make dividend distributions.
Can a corporation claim a loss on a property distribution?
If the FMV of the distribution is less than the corporation’s tax basis, it cannot claim a loss because of the property distribution. Instead it must decrease current E&P by the adjusted basis of the property. When the shareholder receives the property, then the adjusted basis in the property is the property’s FMV, not the corporation’s basis.
How often do companies pay distributions to shareholders?
Distributions are allocations of capital and income throughout the calendar year. When a corporation earns profits, it can choose to reinvest funds in the business and pay portions of profits to its shareholders. Shareholders can receive distributions on a regular basis, such as monthly, quarterly, or annually.
What’s the rule for disproportionate distribution in S-corporations?
S-Corporations with Disproportionate Distribution The general rule is that distributions from S-Corporations to shareholders should be proportional to each shareholder’s ownership interest. By Eric Gros-Dubois Jan