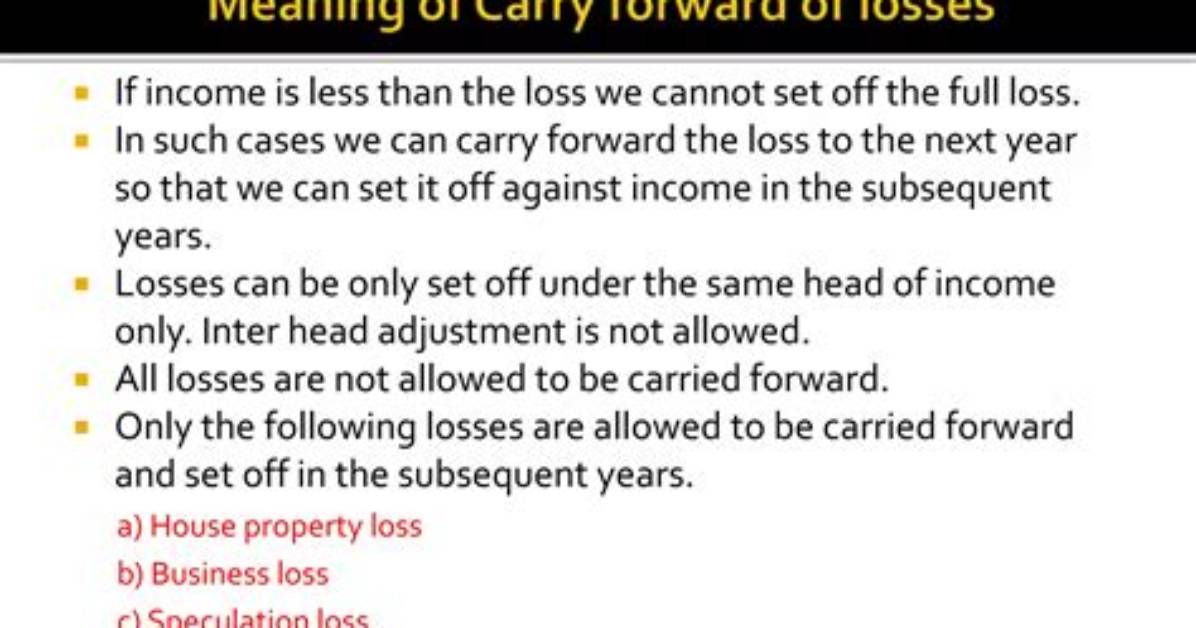
Here is a detailed examination concerning How Much Loss Can Be Carried Forward for Tax Purposes.
There is a Schedule in the K-1 that summarizes the sale, sale date, Initial Basis, Cumulative Adjustments to Basis, Cost Basis (the net of the previous two), Gain subject to recapture, AMT and where on the Federal Filing (Form, Line and Column)

David Miller
Executive Financial & Market Analyst
David Miller brings 15 years of experience in global economics, personal finance strategy, and market dynamics. He specializes in turning complex economic trends into actionable insights for everyday readers.