Is K1 Subject to Self-Employment Tax?
Generally, if you’re a member of a partnership — including an LLC taxed as a partnership — which conducts a trade or business, you’re considered self-employed. General partners pay SE tax on all their business income from the partnership, whether it’s distributed or not.
Is the K-1 income subject to self employment tax?
IRS Says Members’ K-1 Income Subject to Self-Employment Tax. Tax rules which were enacted long before the LLC format came into existence provide that a general partner’s K-1 ordinary business income is subject to self-employment tax, while a limited partner’s K-1 income is not (except for “guaranteed payments”).
How to use Schedule K-1 ( Form 1065 )?
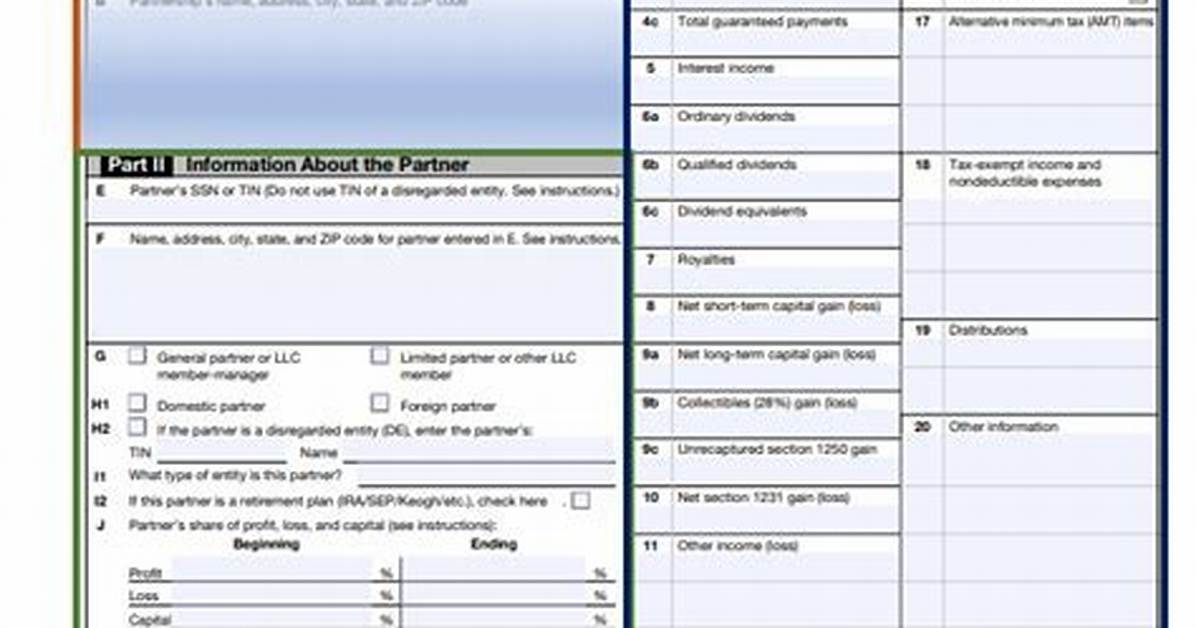
For additional information regarding the requirements for Schedule K-1 (Form 1065) see: Partner’s Instructions for Schedule K-1 (Form 1065). To enter Self-Employment Earnings (loss) from tax form Schedule K-1 (Form 1065) in TaxSlayer Pro from the Main Menu of the Tax Return (Form 1040) select:
How to enter self employment earnings ( loss ) on Form 1065?
To enter Self-Employment Earnings (loss) from a K-1 (Form 1065) in TaxSlayer Pro from the Main Menu of the Tax Return (Form 1040) select: K-1 Input and select ‘New’ and double-click on Form 1065 K-1 Partnership which will take you to the K-1 Heading Information Entry Menu.
Is the income of a limited partner subject to self employment tax?
Tax rules which were enacted long before the LLC format came into existence provide that a general partner’s K-1 ordinary business income is subject to self-employment tax, while a limited partner’s K-1 income is not (except for “guaranteed payments”). So what about an LLC member?