Who Should File Form 3520?
Form 3520-A is the annual information return of a foreign trust with at least one U.S. owner. The form provides information about the foreign trust, its U.S. beneficiaries, and any U.S. person who is treated as an owner of any portion of the foreign trust under the grantor trust rules (sections 671 through 679).
What do you need to know about Form 3520?
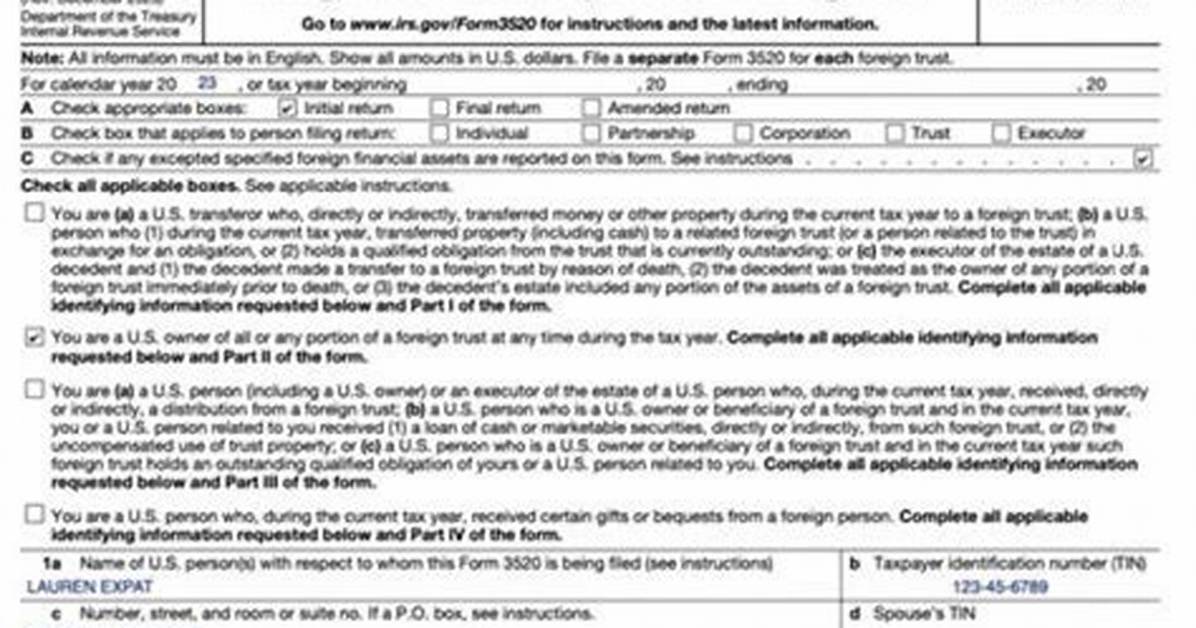
U.S. persons (and executors of estates of U.S. decedents) file Form 3520 to report: Certain transactions with foreign trusts, Ownership of foreign trusts under the rules of sections 671 through 679, and Receipt of certain large gifts or bequests from certain foreign persons.
How to file Form 3520 for an executor?
However, if you are an executor filing a Form 3520 with respect to a U.S. decedent, provide both the name of the Service Center where the decedent’s final income tax return will be filed, and the name of the Service Center where Form 706 will be filed, if applicable. Please enter the information as follows.
Do you have to file Form 3520 as an expat?
There are generally three reasons you might file Form 3520 as an expat: You’re a U.S. owner of a foreign trust (includes the grantor, but could include other people) If you own any part of a foreign trust, you will probably have to file this form. If the answer is “yes,” then you need to file form 3520.